One Tax Strategy Every High-Income Earner Should Understand

So, What’s the Strategy?

One of the questions I hear most often this time of year is:

“Andre, I’m going to make a lot of money this year… what can I still do?”


The answer depends on your situation.

If you’re a business owner, we usually start by looking at strategies inside the business. But if you don’t need to make major investments—or if most of your income comes from a W-2—the list of meaningful tax strategies gets much shorter.

That’s why one strategy has become a frequent topic of conversation in our office this year:

A Properly Structured Short-Term Rental

What makes this strategy unique is that it isn’t limited to business owners, and it doesn’t require you to qualify as a real estate professional like many people assume.

Combined with 100% bonus depreciation and a cost segregation study, a properly structured short-term rental can create substantial first-year deductions for the right taxpayer.

And when I say substantial, I’m not talking about a $20,000 deduction. For many California properties, we’re often discussing potential first-year deductions in the hundreds of thousands of dollars, depending on the purchase price, the results of the cost segregation study, and your specific tax situation.

In the right circumstances, those deductions can offset a significant portion—or even all—of a taxpayer’s ordinary income for the year. That’s what makes this one of the most powerful tax planning strategies available for high-income earners.

Why I Like This Strategy

The tax savings are certainly attractive.

But that’s actually not my favorite part.

One of the reasons I like this strategy so much is that it can accomplish more than one goal at the same time.

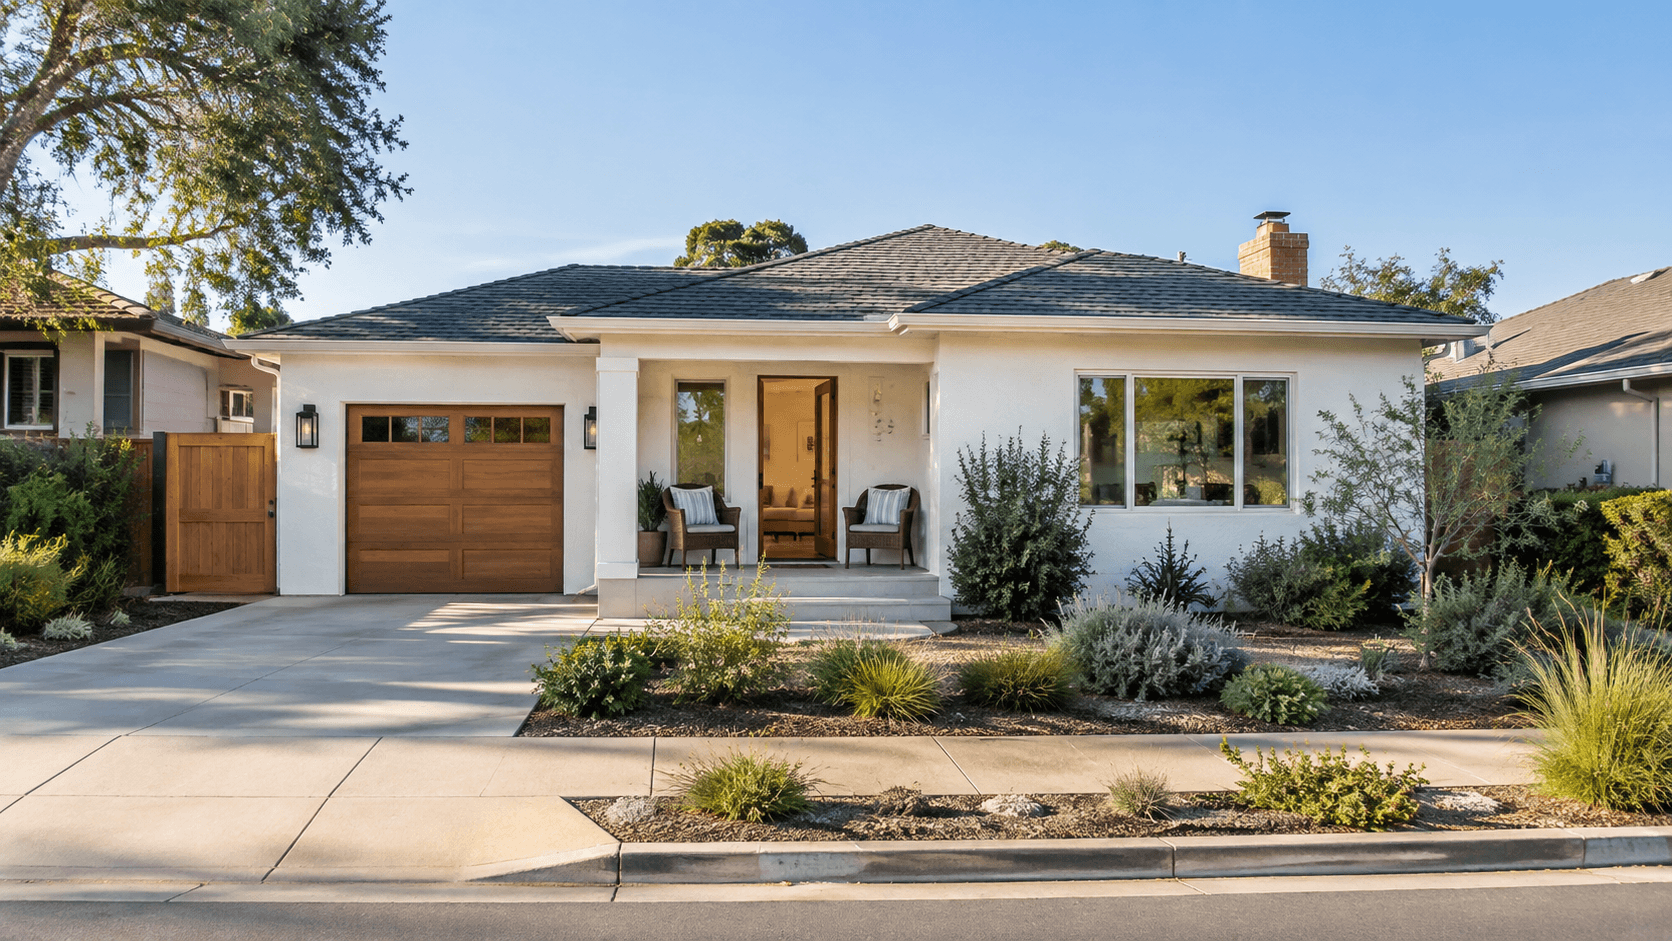
Many of my clients have talked about buying a place in Lake Tahoe, Hawaii, Scottsdale, Dallas, or along the California coast—somewhere they regularly vacation or where they have family.

Instead of buying a second home that sits empty most of the year, what if that property could also become a legitimate investment?

If it’s primarily operated as a qualifying short-term rental, you may still be able to enjoy limited personal use while also benefiting from the tax advantages we’ve discussed.

Now you’ve created an asset that may:

  • Generate rental income.
  • Build long-term equity.
  • Give your family a place to enjoy for years to come.
  • Potentially produce significant tax savings in the year you purchase it.

That’s what makes this strategy so compelling.

The tax deduction is only one of the benefits.

The investment still has to make financial sense on its own.

The Two Rules That Make or Break This Strategy


This is the part that social media usually skips.

Buying a property and listing it on Airbnb doesn’t automatically create a tax deduction.

For this strategy to work, there are two major hurdles that have to be cleared.

Rule #1: The Property Must Qualify as a Short-Term Rental

Generally speaking, the average guest stay needs to be seven days or less. That’s what separates a qualifying short-term rental from a traditional rental property.

Rule #2: You Must Materially Participate

This is the rule that surprises most people.

You can’t simply buy a property, hire a full-service property manager to handle everything, and expect the tax benefits to automatically apply.

The IRS expects you to be actively involved in operating the property. Communicating with guests, managing bookings, coordinating cleanings and repairs, restocking supplies, and overseeing day-to-day operations can all count toward your participation.


For many taxpayers, this means either:

  • Spending more than 100 hours on the property during the year and more time than anyone else involved, or
  • Spending 500 or more hours actively participating in the property’s operations.

Just as important as doing the work is documenting it. Keeping a log of your hours and activities is one of the best ways to support the strategy if it’s ever questioned by the IRS.

Meet these rules, and the strategy can be incredibly powerful.

Miss them, and the tax outcome can be dramatically different.

Why I’m Talking About This in July

This isn’t a strategy you decide to implement in December.

Finding the right property, completing the purchase, preparing it for guests, placing it into service, and coordinating a cost segregation study all take time.

That’s why we’re talking about it now.

If this is a strategy you’d like to explore for 2026, the planning should begin well before year-end.

Your Situation May Need More Than a General Article.

If you’re making a major purchase, dealing with multiple entities, investing in real estate, or trying to understand your tax picture before year-end, tell us what’s going on.

Experienced Support Starts With a Meaningful Engagement.

Pricing depends on the scope, volume, complexity, and level of support your business needs. These are minimum starting points — not typical or average engagement fees.

Bookkeeping

Starting at

$500/month

Most Ongoing Accounting Engagements

Starting at

$1500/month

Individual Tax Return

Individual returns from

$1,200

Business returns from

$1,700

These are minimum starting points, not average fees. Multiple entities, real estate, multi-state activity, transactions, cleanup, and additional planning can increase the scope.

Trusted by Businesses That Expect More From Their CPA

See why business owners choose ManzCPA for proactive guidance,
responsive support, and year-round accounting and tax expertise.

Reviews Marquee

A Few Things You May Want to Know Before Reaching Out.

Clear answers about who we work with, how our services differ, and what to expect from a ManzCPA relationship.

What size businesses does ManzCPA typically work with?

Most of our clients are doing $1M+ in revenue and dealing with real complexity — multiple entities, real estate, multi-state activity, or a business that’s outgrown what a basic bookkeeper or seasonal tax preparer can handle. If that’s where you’re at, we’re a strong fit.

We don’t price off a rate card — we price based on the complexity of your situation and the level of involvement you want from us. That’s why our starting points are just that: starting points. A simple accounting relationship looks different from a multi-entity tax strategy engagement, and the pricing reflects that.

Tax preparation is reporting what already happened — filing the return based on decisions you already made. Tax planning is proactive: reviewing your situation before year-end so we can actually change the outcome. Most CPAs only do the first one. We do both, and we treat planning as its own service, not something that happens for free in a March phone call.

We do prepare individual and business returns, but our clients typically want more than a once-a-year transaction — they want a CPA who understands their business well enough to catch things before they become expensive. If you’re looking for a simple, low-touch filing relationship, we may not be the most cost-effective option for you, and that’s okay.

Personal returns are almost always part of a broader relationship — most of our individual clients are business owners whose personal returns we handle alongside their business returns, entity structure, and planning. We do occasionally take on personal-only returns for high-net-worth individuals with complex situations — investments, multiple income sources, real estate — but a standalone W-2 personal return with no business activity generally isn’t a good fit for our pricing model. If that’s what you need, a firm built around individual returns will likely be a better value for you.

Possibly — but we’re built for businesses managing real complexity: multiple entities, real estate, growing teams, or multi-state activity. If your business is a single entity with straightforward books, you may get better value from a smaller local firm. We’d rather tell you that up front than take you on and not be the right fit.

Bookkeeping and accounting are part of what we do for clients as part of a broader relationship, not a standalone service we compete on price for. If you need a dedicated bookkeeping-only provider, there are firms that specialize in exactly that. What we’re built for is combining clean books with the tax and advisory work that makes those numbers actually useful.

No — and we’d rather be upfront about that than have it become a surprise later. Ongoing accounting and tax engagements cover the scope we agree on together. Deeper advisory work — things like acquisition due diligence, entity restructuring, or standalone tax planning — is scoped and quoted separately based on what you need.

Very. We’re not a firm you hear from once a year in March. Multi-entity and real estate decisions — buying a property, adding an entity, taking on debt — need to be reviewed before they happen, not after. That only works if we’re actually talking throughout the year, not just during filing season.

Yes. We work with clients nationally, with particular depth in high-tax states like California and New York, where the stakes on planning are highest. Our team and process are built to support clients remotely.

We handle it — but it may be scoped separately if it’s outside what we agreed to originally. We’d rather have that conversation directly with you than surprise you with it after the fact.

Tell Us a Little About Your Business.

A few details help us understand what you need before the first conversation.

Tell us who you are and
what you need